
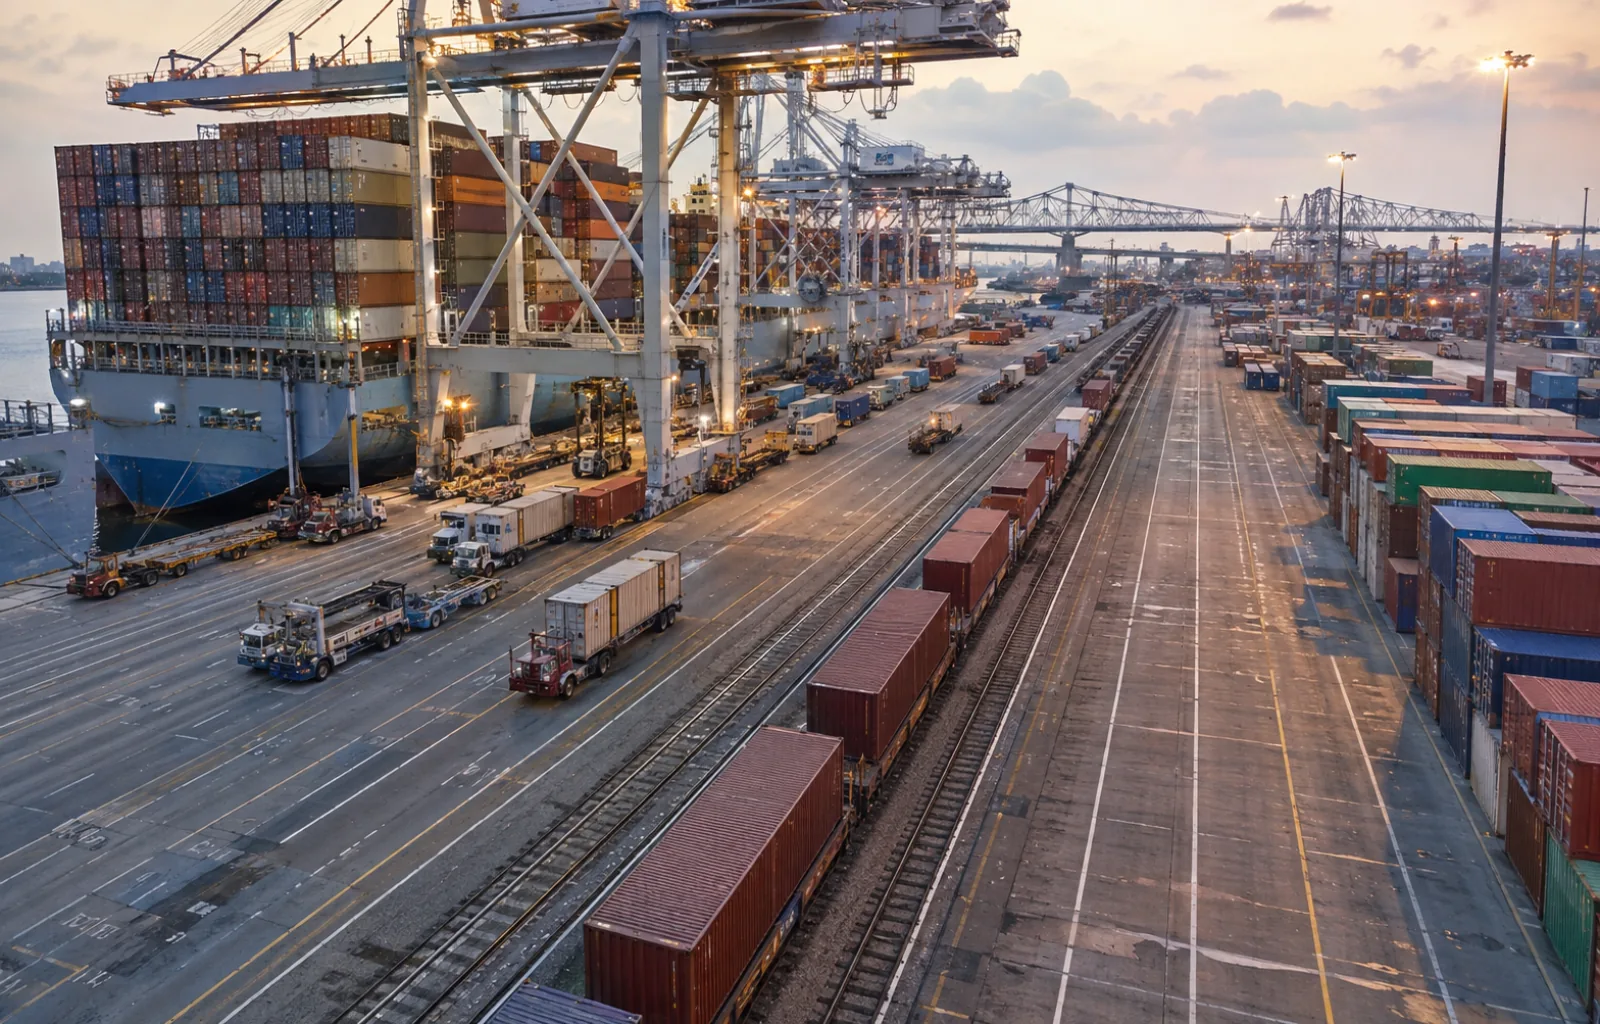
U.S. goods trade opened a wider planning gap between inbound and outbound freight in July. The Bureau of Economic Analysis and Census Bureau reported that goods imports increased $11.4 billion to $320.6 billion while goods exports decreased $6.2 billion to $201.0 billion, on a seasonally adjusted balance-of-payments basis.
The price-adjusted direction was the same. Real goods imports rose $9.3 billion, or 3.8%, to $257.2 billion in chained 2017 dollars. Real goods exports fell $2.7 billion, or 1.8%, to $150.8 billion. That makes the release more than a price-only change, although the real totals still measure broad goods flows rather than shipments, pallets, containers or truckloads.
The commodity mix was concentrated enough to resist a blanket freight conclusion. On a Census basis, computer imports increased $6.9 billion, computer accessories increased $6.6 billion and semiconductors increased $1.2 billion. Crude-oil imports decreased $1.8 billion. On the export side, crude oil fell $4.5 billion and nonmonetary gold fell $3.9 billion, while capital goods increased $1.9 billion and pharmaceutical preparations increased $1.0 billion.
Gold is a particularly important boundary around the headline. BEA replaces exports and imports of nonmonetary gold with a separate adjustment when it incorporates trade statistics into the national accounts. A dollar move driven partly by gold should not be treated as equivalent to a change in recurring freight volume, equipment demand or dock activity.
 See the connected carrier TMS
The North American lanes also split. Seasonally adjusted Census-basis imports from Mexico increased $7.0 billion to $60.1 billion while exports to Mexico slipped $0.2 billion to $32.6 billion. Imports from Canada moved the other way, falling $3.3 billion to $32.5 billion as exports to Canada increased $0.5 billion to $29.3 billion. Those country totals do not identify the mode, gateway, commodity, trailer count or carrier that moved each dollar.
FreightNews infers that an import-up, export-down month can raise the risk of equipment and appointment imbalance around ports, border gateways and inland distribution points. More inbound merchandise does not automatically create a matching outbound load, and a national total cannot show whether a container, chassis, trailer or driver will be positioned where a specific customer needs it. The release establishes a planning signal, not an equipment-shortage finding.
The broader trade balance should be kept separate from the freight question. The combined goods-and-services deficit increased $17.4 billion to $88.6 billion, with total exports down $6.6 billion and imports up $10.8 billion. Services include activity that does not create a physical shipment, so the goods tables and commodity detail are the more relevant starting point for a freight desk.
Carriers, brokers and shippers can test the national split against booked import appointments, export cutoffs, loaded and empty container turns, chassis dwell, border crossing time, trailer balance and customer order releases by gateway. A lane with matched customer flows may avoid the imbalance; an import-heavy lane without a backhaul can lose the apparent volume benefit to empty repositioning and time.
The agencies revised January through June trade estimates with this release, and July figures will remain subject to later revision. Keep the September 3 release vintage beside any forecast. The defensible operating conclusion is that real inbound goods flow strengthened as real outbound goods flow weakened in July; the profitable response still depends on the exact commodity, mode, gateway and return plan.