

A smaller fleet and fewer seated trucks did not restore a comfortable margin. The American Transportation Research Institute's latest national benchmark put 2025 truck operating cost at a record $2.336 per mile.
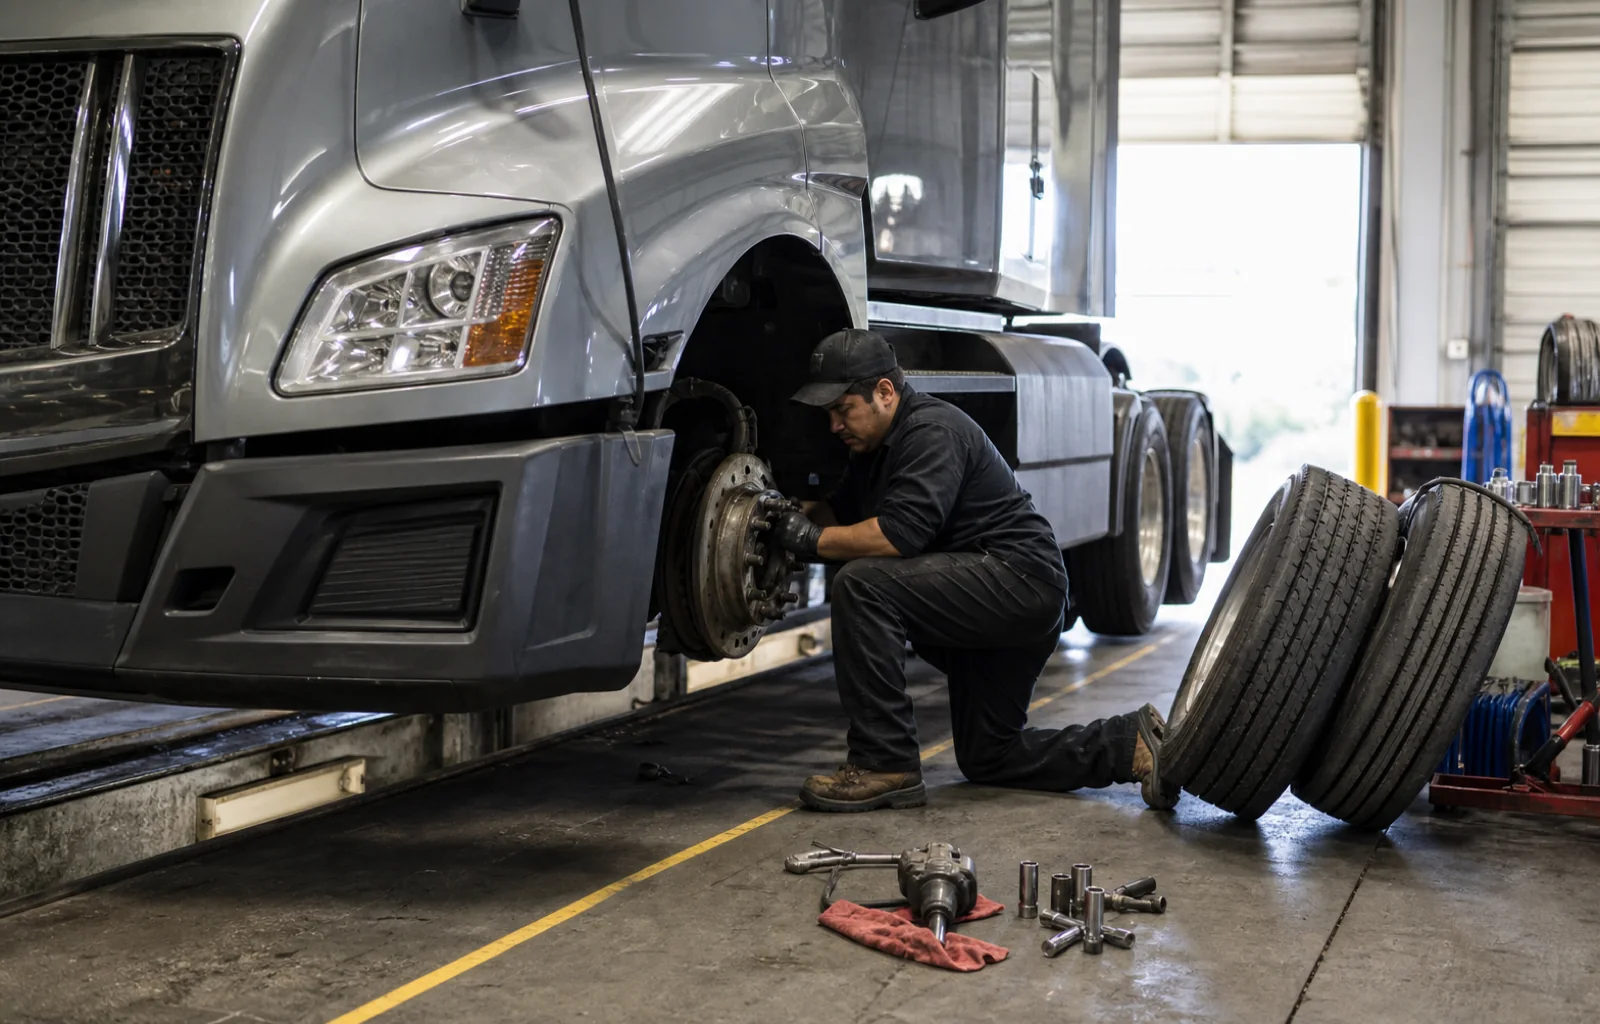
Fuel was not the main accelerant. Excluding fuel, cost increased 4.2% to $1.854 per mile. ATRI reported that every major line item rose, led by tolls at 13.2%, repair and maintenance at 8.6%, driver benefits at 6.6% and tires at 6.4%. Fuel and driver pay were the only categories that rose at rates below inflation.
Carriers were already cutting capacity and utilization. ATRI said respondent truck counts fell 2.4%, and an average 10% of trucks were left unseated. Yet USDA's August 20 Grain Transportation Report, which highlighted the benchmark, said operating margins for the truckload and refrigerated sectors improved only slightly and remained below 1%; tank carriers averaged 4%.
Those figures describe 2025 respondent operations, not a universal 2026 bid rate or a census of every carrier. Cost per mile changes with region, duty cycle, trailer type, fleet size, insurance program and the share of empty or unpaid miles. The benchmark also cannot show whether a specific lane is profitable at today's rate.
FreightNews infers that the next stage of a freight-rate recovery can still leave carriers below their own cost floor. If linehaul revenue improves while maintenance, toll, tire and benefit expense remain elevated, a higher rate can narrow a loss without creating an adequate return. That is an operating interpretation of ATRI's benchmark, not a forecast that rates or margins will move by a particular percentage.
A useful internal comparison starts with the same denominator. Fleets should calculate cost per dispatched mile, loaded mile and tractor day; separate fuel surcharge from linehaul; and bridge maintenance, tires, tolls, insurance, benefits and equipment ownership against 2024. Mixing loaded-mile revenue with all-mile expense can make an apparent recovery disappear when empty miles are added back.
Maintenance deserves a second view by asset age and failure type. A higher shop total can reflect planned work that prevents road failures, unplanned downtime that destroys utilization, or both. The invoice amount alone does not distinguish the operational result.
The capacity figures need the same discipline. Fewer trucks and more unseated equipment do not automatically prove a shortage: parked tractors may be excess, unavailable, awaiting repair or positioned outside the lanes a shipper needs. Tender acceptance, dwell, service failures and lead time are better tests of whether usable capacity is actually tightening in a network.
For the fall planning round, the practical question is not whether $2.336 belongs in every rate sheet. It is which cost lines changed in a fleet's own operation and whether contribution per tractor is clearing them. A national record matters as a comparison point; the go-or-no-go decision still belongs to lane-level revenue, utilization and cash cost.